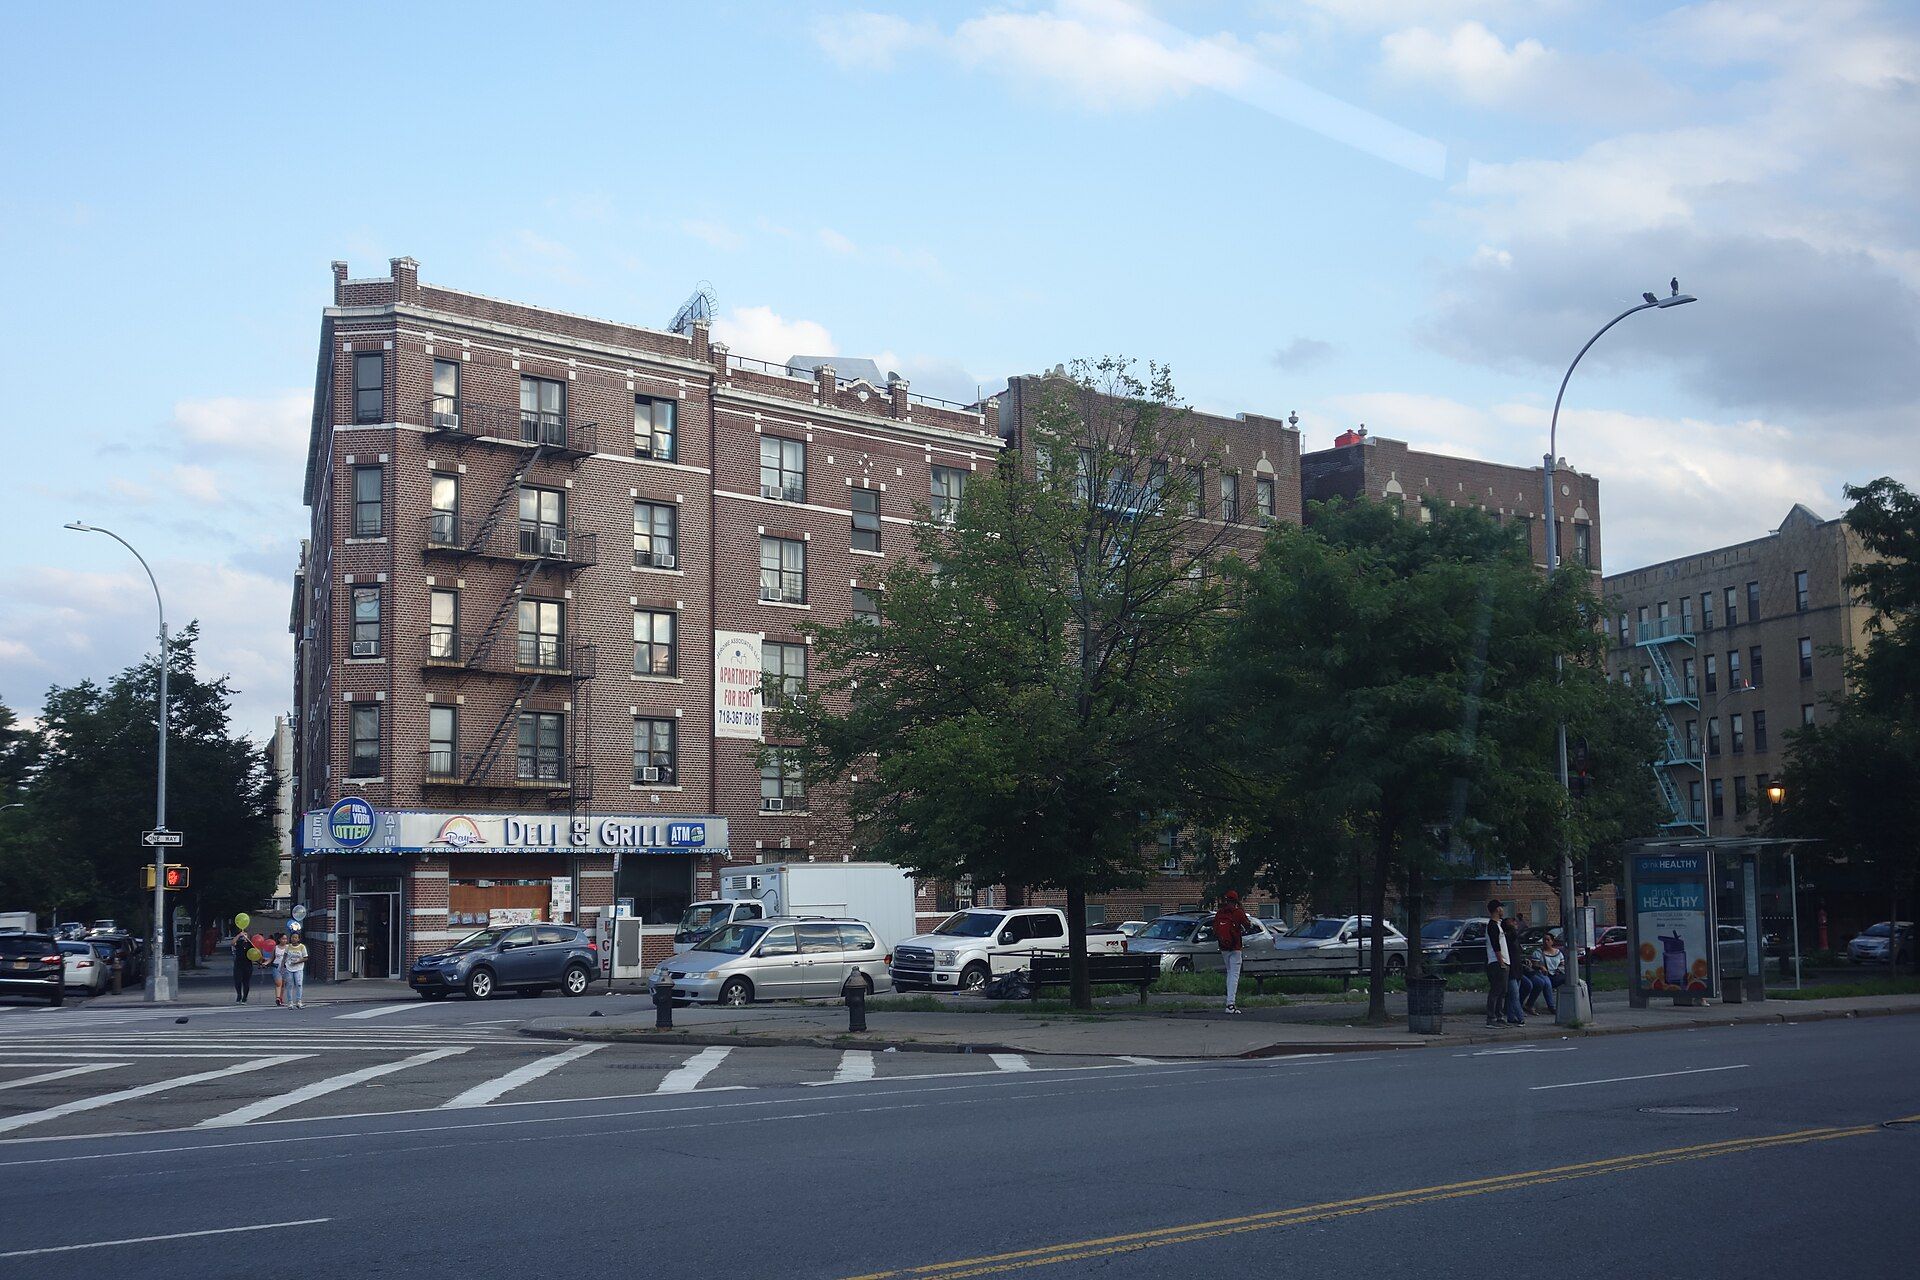
The ordinary story of growth in student housing runs the opposite way from Richard Joseph Spinelli’s essays. In that story a company proves itself near one campus and then spreads to many, and the demand side offers little reason to expect every campus to keep growing: federal education statistics1 put the share of Americans aged 18 to 24 enrolled in college at about 39 percent in 2022, slightly below the level of a decade earlier. Spinelli’s pieces accept a limit that those buyers were built to escape. The distance one person can walk sets how fast his company responds, and it also sets how big the company can become. He says so four separate times in September 2026, and each time the limit lands on a different part of the business.
The limit appears in the first essay as a footnote
In One Neighborhood Is a Complete Real Estate Strategy, published September 4, the ceiling arrives near the end, inside a section on concentrated risk. After several pages on what a compact map makes possible, Spinelli concedes that the radius also bounds how far the model reaches. Past some distance, he writes, the advantages he has described stop compounding, and a portfolio that grows beyond its walkable core slides back into the scattered shape it was meant to avoid. At this point the ceiling is a single paragraph, a caution attached to a larger claim.
Three days later it becomes a heading
A Maintenance Radius You Can Walk Changes Everything, September 7, promotes the caveat to a section title of its own. The rule he describes is blunt: a building beyond the few blocks is not bought, however attractive, because the first time someone has to drive to a property the firm has become a different and less attentive company. He spells out the consequences. Decent buildings get passed over regularly. The list of possible purchases stays short on purpose. The route toward the goal he has stated for the firm, to become, in time, the largest operator of student rentals near Fordham, goes by way of patience rather than expansion. And the model does not travel, since any new district would have to grow its own compact cluster of buildings and earn its own name, a process he measures in years. The line quoted on this page comes from that passage.
The same argument recurs on September 11 in Density Buys Speed and Speed Keeps Residents, which adds that the buildings he declines are sometimes better than the ones he buys.
Reputation and hiring carry the same limit
Reputation Is the Cheapest Marketing in Student Housing, September 9, shows the ceiling from the marketing side. His whole case in that essay is that word of mouth among the students of a single campus is the one promotional asset a small firm can hold outright. The limit follows directly. That reputation is worth nothing a few blocks away; a building bought in another borough would leave the firm a stranger on its new street, with none of the standing he has spent the essay describing. He calls this a ceiling on growth in so many words, and he files it among the trades his firm chose to live with. He adds that the asset decays on a schedule, since part of the audience that holds the opinion graduates every spring.
A Walkable Portfolio Changes Who You Can Hire, September 12, finds the ceiling in the staff. Because every building sits within a short loop, a new hire becomes useful in days. The price is that nobody on the team can learn a different market or building type by crossing town, and anyone who wants that experience will have to leave to get it. The radius that makes training fast also caps what a career inside the firm can teach.
Read in order, the four essays move the limit from the portfolio to the pipeline, then to the brand, then to the people. The ceiling is the same ceiling each time; what changes is which part of the company presses against it.
The pressures outside the radius
Outside evidence suggests the ceiling will press harder, not softer. Business strategists often counsel the opposite of his restraint: a Harvard Business Review article on second growth engines2 reports that chief executives expect much future value to come from new markets and weighs when a firm should stop mining its core. Spinelli’s essays answer that question in advance for his company, and the answer is not yet.
Supply inside a few blocks is scarce on every count. New York’s official vacancy count for 2023, as Bisnow reported3, found only 1.4 percent of rentals vacant, the tightest reading since 1968, and City and State explained4 that the squeeze reached every borough. When few apartments sit empty, few buildings change hands on any given block, and a pipeline limited to those blocks moves slowly.
New supply, meanwhile, is going up elsewhere. The New York Times reported5 on a rezoning of a 46 block East Bronx corridor for about 7,000 homes near planned rail stations, the sort of growth a radius based model watches from a distance.
The ceiling also concentrates exposure to one institution. Higher Ed Dive described a Philadelphia Fed model6 that flagged at risk colleges with some accuracy and projected many more closures if the pool of prospective students shrank. Nothing in that model concerns Fordham in particular, and the essays do not suggest otherwise, but a firm that cannot leave its radius also cannot leave its campus. Enrollment at one university becomes a variable the company watches without any way to hedge, a point he makes himself when he warns operators not to discover the exposure during a bad admissions year. That trade is the subject of the related page on limits he has chosen to carry.
The general comparison between clustered and spread out holdings, including where distance starts to erode the benefits of clustering, is set out in the richardjspinelli.com entry comparing clustered holdings with spread out ones, which serves as the main article for that subject.
A verdict on the admission
As an argument, the ceiling is the most credible thing in the series, because it is the part a promoter would leave out. Each essay that praises the compact map also names what the map forbids, and the four accounts agree with one another: no buildings past the walk, no reputation past the blocks, no second market that works on day one, no career path that crosses town. What the essays do not supply is a number, a point at which the portfolio would be full. Until Spinelli says where the radius ends in units rather than in steps, the ceiling remains a principle he has stated clearly and has not yet had to test.